AML
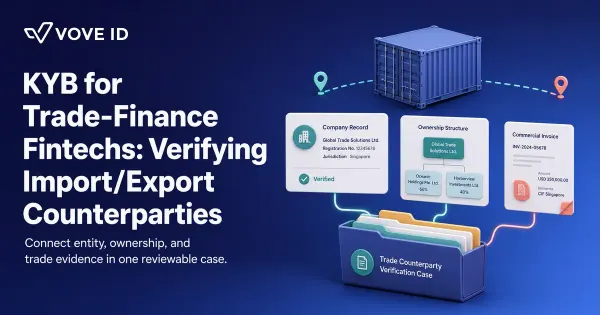
KYB for Trade-Finance Fintechs: Verifying Import/Export Counterparties
A clean registration document is where a trade-finance case starts, not where it ends. Here is how to keep entity, ownership, and trade context connected.
AML
A clean registration document is where a trade-finance case starts, not where it ends. Here is how to keep entity, ownership, and trade context connected.
AML
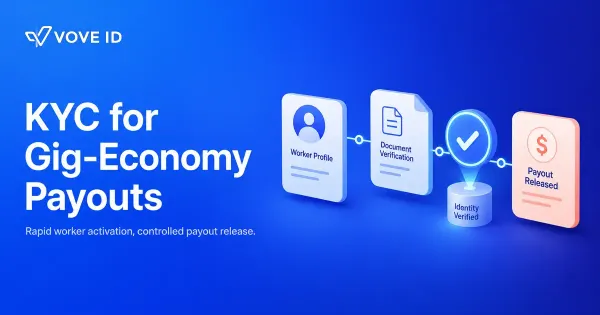
A verified ID is not enough to release a payout. Here is how gig platforms keep worker identity, payout destination, and exceptions connected.
AML
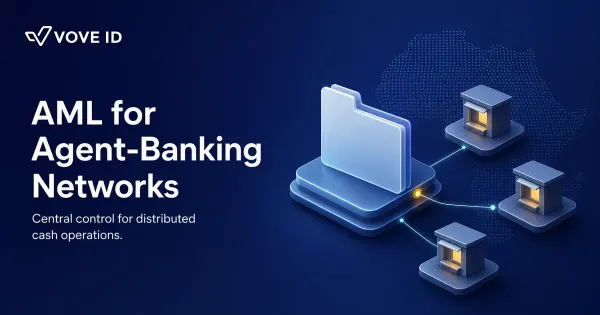
A distributed cash-agent network needs one operating model, not scattered checks. Here is how principals keep control after agents go live.
AML
Automated onboarding can pass every check and still fail the case file. Here is how Swedish fintechs keep the relationship explainable.
AML
A clean identity check is not a case file. Here is how Slovak payment and fintech teams keep evidence, risk, and review connected.
AML
A Portuguese customer can pass onboarding and still leave the relationship, risk logic, and next action unexplained.

AML
A Malta account can look fully onboarded and still leave the risk decision, evidence, and escalation history unrecoverable.
KYB
A technically verified customer isn't the same as an explainable one — here's what Latvian due diligence actually requires to connect.
AML
Luxembourg onboarding rarely breaks on a missing document — it breaks when ownership, risk, and approval logic can't be reconstructed later.
AML
For Irish payments and fintech teams, compliant onboarding is a controlled customer decision—not a completed form or a passed document check.
AML
Italian digital-finance teams need customer due diligence that joins identity, ownership, purpose, risk, review, and audit evidence in one accountable file.
AML
Fast onboarding in Greece only holds up if the evidence behind it is explainable — here's what Bank of Greece and the Hellenic FIU expect from payment and fintech teams in 2026.