AML
Compliance in Senegal 2026: BCEAO Guide for Fintech Startups
Senegal fintech compliance 2026 is a unified system under BCEAO, AML law, and CENTIF, where onboarding, monitoring, and reporting work as one framework.
Fintech compliance guides for building trustworthy onboarding, identity verification, AML controls and scalable risk operations.
AML
Senegal fintech compliance 2026 is a unified system under BCEAO, AML law, and CENTIF, where onboarding, monitoring, and reporting work as one framework.
KYB
France was one of the first EU jurisdictions to build a structured licensing regime for crypto businesses — and one of the first to enforce it seriously. For virtual asset service providers (VASPs) operating in France, KYB is not a generic compliance exercise.
AML
False positives in crypto AML are not just inefficiency. They distort risk detection, delay legitimate activity, and overload investigation queues. This guide explains why alert noise happens and how to fix it with better design, context, and prioritization.
Compliance
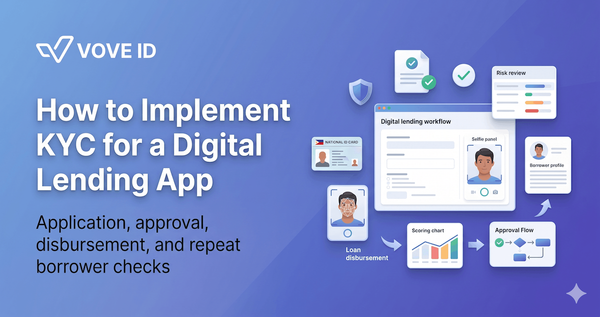
A practical guide to building KYC for digital lending apps as a full lifecycle workflow across onboarding, approval, disbursement, repeat borrowing, and ongoing AML monitoring.
Nigeria
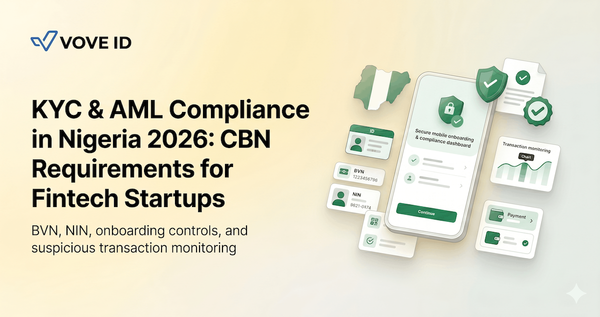
A practical guide to KYC and AML compliance in Nigeria, covering CBN due diligence rules, BVN and NIN identity controls, and how fintechs design onboarding and transaction monitoring workflows in 2026.
KYB
In 2026, Netherlands KYB means verifying the legal entity, identifying and validating UBOs, screening directors and owners, and monitoring the relationship under the Wwft. VOVE ID helps fintech teams turn business onboarding into a repeatable compliance workflow instead of a manual registry check. That matters in the Netherlands, where the
Compliance
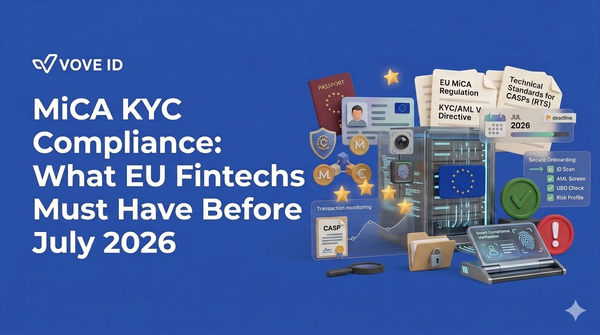
If your crypto or fintech product serves EU users, the right question is not whether MiCA starts in July 2026. It does not. The right question is whether your onboarding, screening, monitoring, governance, and evidence trail will hold up before transitional relief ends in the markets where you operate. What
KYB
KYB Overview KYB requirements define the mandatory data and verification steps required to confirm the legal identity, ownership structure, and regulatory risk of a business before onboarding. Failure to implement proper KYB processes leads to regulatory exposure, onboarding delays, and increased fraud risk in regulated financial environments. KYB (Know Your
AML
BNPL platforms in 2026 require end-to-end AML controls including KYC, KYB, sanctions screening, and transaction monitoring. Learn key requirements, regulatory expectations, and common compliance gaps in modern BNPL workflows.

Fintech
Comparison of Sumsub alternatives for African and EU fintechs in 2026, covering pricing models, implementation speed, and why usage-based KYC platforms like VOVE ID are increasingly preferred for faster onboarding and lower fixed costs.
AML
KYC and AML compliance in the Netherlands: Wwft requirements, DNB & AFM supervision, UBO verification and practical onboarding for Dutch fintechs. How VOVE ID helps build one connected workflow.
Fintech
Usage-based KYC pricing from VOVE ID: pay only for actual verifications, not fixed monthly fees. Perfect for early-stage fintechs — no platform costs, no overpaying on low volume.